Let’s say that a fairy waved a magic wand and $10,000,000 appeared in my bank account. I get to put the money in the stock market as I please.
Which stocks would I choose? What are the best stocks to put one’s money in?
First off, what is a stock? Simply put, a stock is the ownership of a portion of a company. Company A is worth $5 billion. You have $250,000 worth of stock in said company. This means that you own a tiny portion of the company – 0.005% to be precise.
You could just leave excess money in a savings account for an average percentage yield (APY) of 0.61%. Or, you can choose a company like Chevron with an annual dividend yield (ADY) of over 4%.
In layman’s terms, APY and ADY represent the amount of money you receive per year based on, but not directly from, the principal amount. In return for outsourcing $10,000, would you rather receive $61 per year or $400 per year?
An advantage of choosing a reputable business over a bank to store money is that the principal can increase without you having to add extra money.
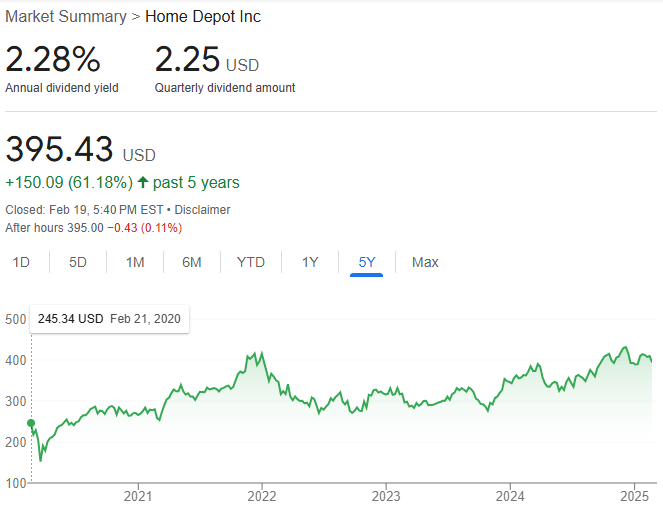
An example of this is Domino’s Pizza. In November of 2015, the pizza chain was worth $3.7 billion; now (2025), $16.46 billion. This means that the corporation is today worth about 4.45 times as much as it was 10 years ago. Had you put $50,000 in a decade ago, it would now be approximately $222,500. And remember, that’s just the principal.
Of course, a disadvantage of placing money into a stock is that the value of the respective company could decrease. In other words, you lose money.
This is why one ought to “diversify their portfolio,” which is a fancy way of saying to split the money into multiple investments. Don’t pick only one company to hold your stocks. Or, as farmers used to say in the good ol’ days: Don’t put all your eggs in one basket.
How do you know which companies to choose? You can never know 100% for sure how a company will perform in the long run. Therefore, I’d suggest searching for Fortune 500 companies due to their durability and proven track records.
Yes, a corporation of even McDonald’s caliber could go out of business in our lifetimes, but the chance is no less slim than a sock string.
Don’t forget that Uncle Sam will be expecting 15 or 20% of the revenue in the form of capital gains tax from any qualified dividend that you earn. Therefore, that $58,000 will shrink to $46,000. $46,000 is $3,867/month. Also, keep in mind that, unlike wages (W2), capital gains (1099-DIV) are not withheld automatically. You are responsible for remembering to pay the IRS its share.
I would then research the ADY of other Fortune 500 companies and allocate money accordingly; $1 million here, $500,000 there, $700,000 there, etc. I’d end up making somewhere between $250,000 and $500,000 in revenue per year.
This would allow me to live off the dividends via semi-passive income. I don’t prefer the term “passive income.” The stocks must still be overseen. It also takes work to discipline oneself into not touching the principal amounts. For some temperaments, it’s easier; others, harder.
If you are one of those people who struggle with self-control, then I’d suggest strengthening your mind. Perhaps strength train at a gym, get into yoga, or take martial arts. Also, a financial planner may help alleviate any lack of perspective you may have.
If you ever hear about a “withdrawal rate,” then know that it involves taking from the principal amount. Apparently, both Dave Ramsey and Suze Orman mentioned it upon giving retirement advice. The former stated that you need only $1 million to retire; the latter, $5 million or $10 million.
My thinking is, with $10 or even $5 million, why on earth would you even touch the principal unless you see the stock going down?
We all know that money just simply isn’t what it used to be due to inflation, but still – investing even $5 million for an average yearly return rate of 3% generates $150,000/year in revenue.
Remember also that assets protect an owner from the effects of inflation. This is why “the rich get richer and the poor get poorer,” as they say.
Anyways, what are these financial experts or so-called “gurus” seeing that I, along with you as well, am not seeing?
Check out the video below.